
Our first equity research report covers Lonza, the Swiss company that builds and runs the factories behind other companies’ drugs. The full six-page report is below.
SGMS view
Hold
Share price
CHF 663.60
Fair value
CHF 667
Range, bear to bull
CHF 507 to 801
Executive summary
Lonza has had a strong 2026. First-half sales grew 16% at constant currency, the CORE EBITDA margin reached 34.8%, and in October management raised its mid-term margin target to the high thirties. The shares are up 23% this year.
We take that guidance at face value, about 11% growth a year and a 38% margin by 2031, and get a fair value of CHF 667, in line with the share price. A reverse DCF shows that CHF 664 already pays for that guidance in full, with nothing left for a stumble, and 53% of our 20,000 Monte Carlo runs end below the price.
We start at Hold and would buy below CHF 575.
Three things to know
- Margins should rise another four to five points by around 2031.
- Vacaville, bought from Roche in 2024, could more than triple its sales to CHF 2bn in the early 2030s, but should stay flat until 2028.
- CHF 403 of the CHF 664 share price is growth that has not happened yet.
Exhibit 1
Our values cluster around the price. Only the brokers sit clearly above
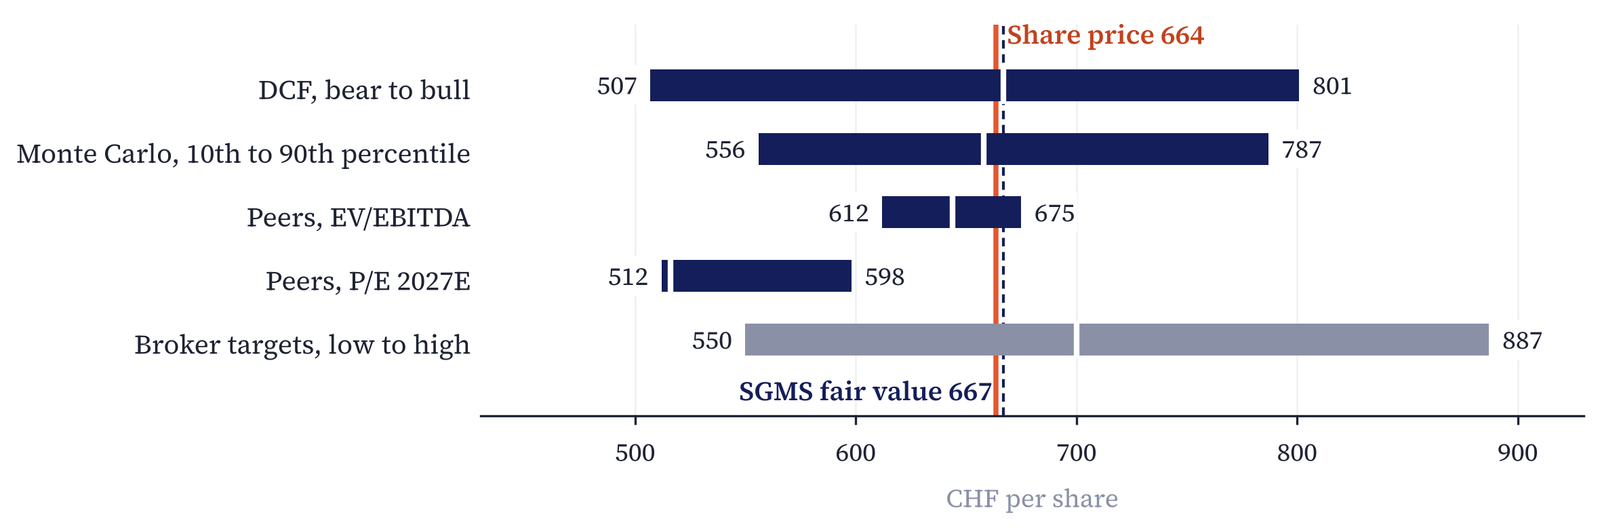
White ticks mark the central value, the red line the share price. Source: SGMS estimates; peers from StockAnalysis (Oct 2026); broker targets from MarketScreener and cash.ch (Oct 2026): CHF 550 to 887, average about CHF 700.
Read the full report
Written by students for education. This is not investment advice. Prices as of the close on 11 November 2026.
